
X Change: Stablecoins, Tokenised Deposits & Banking Infrastructure
OCBC introduces 24/7 tokenised-deposit treasury transfers, Independent Reserve expands cross-border payments, and new data shows growing commercial use of stablecoins.
X Change is BetterX and AUDX’s weekly briefing on digital assets, stablecoins, payments and financial infrastructure.
Stablecoins are increasingly becoming part of the infrastructure businesses use to move money.
This week's developments provide several examples of how that is taking shape.
In Singapore, OCBC has launched a tokenised-deposit solution with Ant International to support cross-border treasury management. Independent Reserve has introduced new business payment services, while Fiserv has brought stablecoin infrastructure into its existing banking technology platform.
New research from Visa and CoinDesk also provides a clearer picture of where stablecoins and tokenised assets are gaining traction.
The common theme is practical implementation: connecting digital money with banking, payments and treasury operations that businesses already use.
Here's what caught our attention.
🏦 Banking & Digital Money
OCBC and Ant International launch 24/7 tokenised-deposit treasury transfers
OCBC has introduced a tokenised-deposit solution with Ant International, enabling round-the-clock treasury management and liquidity movement between Singapore and Malaysia.
The solution operates through Ant International's WhaleRTP, a blockchain-based wholesale settlement platform.
Initially, Ant International will be able to move Singapore-dollar and US-dollar tokenised deposits between its entities, supporting near-real-time treasury settlement outside traditional banking hours.
The arrangement is designed to improve how Ant International manages liquidity across its businesses, reducing operational constraints associated with banking cut-off times and settlement windows.
Why it matters
This is a practical example of tokenised deposits being applied to corporate treasury rather than simply demonstrated through a banking pilot.
For multinational businesses, liquidity can become fragmented across countries, currencies and banking systems.
Being able to move funds between entities outside normal banking hours may help treasury teams deploy working capital more efficiently.
Importantly, the initial solution supports Ant International's own treasury operations. It should not be confused with a general-purpose cross-border payment service available to all businesses.
Source: OCBC, 7 October 2026.
💳 Payments Watch
Independent Reserve expands into business cross-border payments in Singapore
Independent Reserve has expanded its Singapore offering to include cross-border payment services for businesses, enabling companies to make international payments using fiat currencies and stablecoins.
The service supports more than 20 currencies, including major G10 and several ASEAN currencies.
Businesses can fund their accounts in SGD or USD and make payments to overseas suppliers, employees and corporate entities in their local currencies. The platform also allows businesses to receive stablecoin payments, including USDC and USDT, and offers API connectivity to automate transactions and simplify reconciliation.
Independent Reserve says payments can settle on the same day, although actual processing times depend on the currency, destination and payment method.
Independent Reserve is also an existing trading venue for AUDX, our Australian dollar stablecoin, which is available on its Australian platform.
While AUDX has not been announced as part of Independent Reserve's new Singapore cross-border payments service, the expansion reflects the broader development of payment infrastructure that can connect stablecoins with traditional banking and local currency settlement.
Why it matters
One of the biggest challenges in stablecoin adoption isn't transferring tokens between wallets. It's connecting those transfers with the financial systems businesses already use.
Companies need access to banking, currency conversion, liquidity, compliance and local payout infrastructure.
Independent Reserve's expansion demonstrates how digital asset providers are bringing these capabilities together, allowing businesses to access stablecoin-based payment services without necessarily managing the underlying blockchain transactions themselves.
For Australian-dollar stablecoins, the longer-term opportunity is particularly relevant: enabling AUD-denominated value to move through international payment networks without every transaction first needing to be converted into a US-dollar stablecoin.
The next step will be ensuring that AUD liquidity, conversion services and local payout infrastructure are sufficiently developed to make these transactions practical at scale.
Sources: Independent Reserve — Singapore Payments Announcement, 6 October 2026 | AUDX on Independent Reserve
🪙 Stablecoin Infrastructure
Fiserv brings stablecoin infrastructure into its banking platform
Fiserv has announced that its digital-asset platform is live with financial institution clients.
The platform's first live use case is Roughrider Coin, a US-dollar-backed stablecoin designed to support interbank payments in North Dakota.
The project involves the Bank of North Dakota, VersaBank, Solana and Fireblocks.
VersaBank serves as the stablecoin issuer, while Fireblocks provides digital-asset infrastructure and tokenisation services.
Participating banks and credit unions can access the solution through Fiserv's existing commercial banking platform.
The Bank of North Dakota says the initiative provides a new way for its network of more than 90 participating banks and credit unions to move money.
Why it matters
The significance lies in how the technology is being delivered.
Rather than requiring financial institutions to build their own blockchain infrastructure, Fiserv is incorporating stablecoin capabilities into software that banks already use.
This is an important distribution model.
Many regional banks and financial institutions may have legitimate use cases for digital money but lack the resources to develop and maintain the underlying infrastructure themselves.
Embedding stablecoin capabilities within established banking technology could lower the operational barriers to adoption.
It also demonstrates that stablecoin infrastructure is no longer being developed exclusively by cryptocurrency exchanges and blockchain-native companies.
Source: Fiserv, 1 October 2026.
📊 Stablecoin Adoption
Visa reports growing business use of stablecoin-linked cards
Visa has published new data showing that business and commercial card programmes accounted for approximately 17% of stablecoin-linked card volume during its 2026 financial year to date.
Visa currently supports more than 160 stablecoin-linked card programmes across consumer, business and commercial use cases.
According to the company, payment volume across these programmes has grown nearly 200% year on year.
Visa also highlighted increasing interest in stablecoins for treasury management, supplier payments, payouts and cross-border commerce.
Why it matters
Stablecoins have historically been associated with digital-asset trading and exchange settlement.
These figures suggest that commercial payment activity is becoming a more visible part of the market.
However, the numbers require some context.
The 17% figure represents the business and commercial share of Visa's stablecoin-linked card volume. It does not mean stablecoins account for 17% of Visa's overall business payments.
Similarly, growth in stablecoin-linked card volume should not be interpreted as equivalent growth in all stablecoin payments.
Nevertheless, the data provides a useful indication of how stablecoin infrastructure is expanding into business payment products.
Source: Visa, 1 October 2026.
🌍 Global Payments
Stripe plans to expand stablecoin-linked cards to more than 100 countries
Stripe is planning a significant international expansion of its stablecoin-linked card business.
According to comments reported by CoinDesk, the company aims to extend availability to more than 100 countries by the end of 2026.
The announcement comes as Stripe continues expanding its digital-asset capabilities following its acquisitions of stablecoin infrastructure provider Bridge and wallet technology company Privy.
Stripe is also exploring opportunities involving tokenised deposits and decentralised financial infrastructure.
Why it matters
The potential reach of stablecoin-enabled payments is changing.
For businesses operating internationally, the value proposition is not necessarily about adopting a new currency.
It is about accessing payment and settlement infrastructure that can support multiple markets without requiring a separate banking integration in every jurisdiction.
Stripe's expansion plans illustrate how large payments companies are positioning stablecoins within their broader financial infrastructure strategies.
However, the proposed geographic expansion remains a target, not a completed rollout. Actual availability will depend on implementation and applicable market requirements.
Source: CoinDesk, 5 October 2026.
📈 Digital Asset Markets
Stablecoin market reaches US$313 billion as tokenised-equity trading grows
CoinDesk Data's September 2026 Stablecoins & Tokenized Assets Report provides an updated view of activity across digital money and tokenised financial products.
The report found that total stablecoin market capitalisation increased 1.29% during September, reaching approximately US$313 billion.
Trading volume across stablecoin pairs on centralised exchanges exceeded US$1 trillion, the first monthly reading above that level since March.
Meanwhile, on-chain trading volume for tokenised equities increased 16.4%, reaching a record US$15.6 billion.
Robinhood became the largest venue by reported tokenised-equity trading volume during the period.
Why it matters
These figures highlight two developments worth watching.
First, stablecoins remain an important source of trading and settlement activity within digital-asset markets.
Second, tokenised financial products are attracting measurable trading activity as more platforms introduce blockchain-based representations of traditional assets.
There is an important distinction between the two.
Stablecoin market capitalisation measures outstanding supply, while trading volume measures transaction activity. Neither figure should be treated as equivalent to payment adoption.
Similarly, rising tokenised-equity trading volume does not necessarily establish that institutional investors are adopting tokenised securities at the same rate.
Nevertheless, the figures provide useful evidence of activity across two important segments of digital finance.
Source: CoinDesk Data, 6 October 2026.
💡 X Change Perspective
The next stage of stablecoin adoption is about distribution
For several years, much of the stablecoin discussion centred on issuance.
- Which companies would launch stablecoins?
- How would reserves be managed?
- Which currencies would be represented on-chain?
Those questions remain important, particularly as regulatory frameworks develop. But the more interesting developments increasingly concern what happens after a stablecoin has been issued.
- How does it reach businesses?
- How does it connect with bank accounts?
- Who provides currency conversion and local payouts?
- How does it integrate with existing treasury and accounting systems?
This week's announcements from Independent Reserve, Fiserv and Stripe all address different parts of that challenge.
OCBC's work with Ant International demonstrates a parallel development in tokenised bank deposits, where financial institutions are applying similar technology to corporate liquidity management.
These are different models, but they share a common objective: making digital money useful within existing financial operations.
The next phase of adoption may therefore depend less on how many new stablecoins are launched and more on how effectively financial institutions and payment providers can integrate them into services businesses already understand and use.
That is where the commercial opportunity and the operational complexity increasingly sits.
🇦🇺 What does this look like in Australian dollars?
The growing interest in stablecoin-based payments and settlement raises an important question for businesses working with Australian dollars.
How can AUD-denominated value move efficiently across digital-asset markets and blockchain-based financial infrastructure?
AUDX is an Australian dollar stablecoin designed to support AUD-denominated payments, settlement, treasury and digital-asset activity.
It provides a way to hold and transfer Australian-dollar value on-chain, without first converting that value into a US-dollar stablecoin.
You already use Australian dollars.
AUDX simply lets you use them in more places.
For payment providers, exchanges, brokers and businesses operating across digital financial markets, AUDX can provide an Australian-dollar settlement asset within supported blockchain environments.
Its practical use depends on the availability of appropriate liquidity, conversion services and payment infrastructure.
AUDX is 1:1 AUD backed
Learn how AUDX works, where it's available and the use cases it can support.
⚓ BetterX & AUDX at TOKEN2049 Singapore
Bringing the conversation together: Payments, Yield and Digital Assets
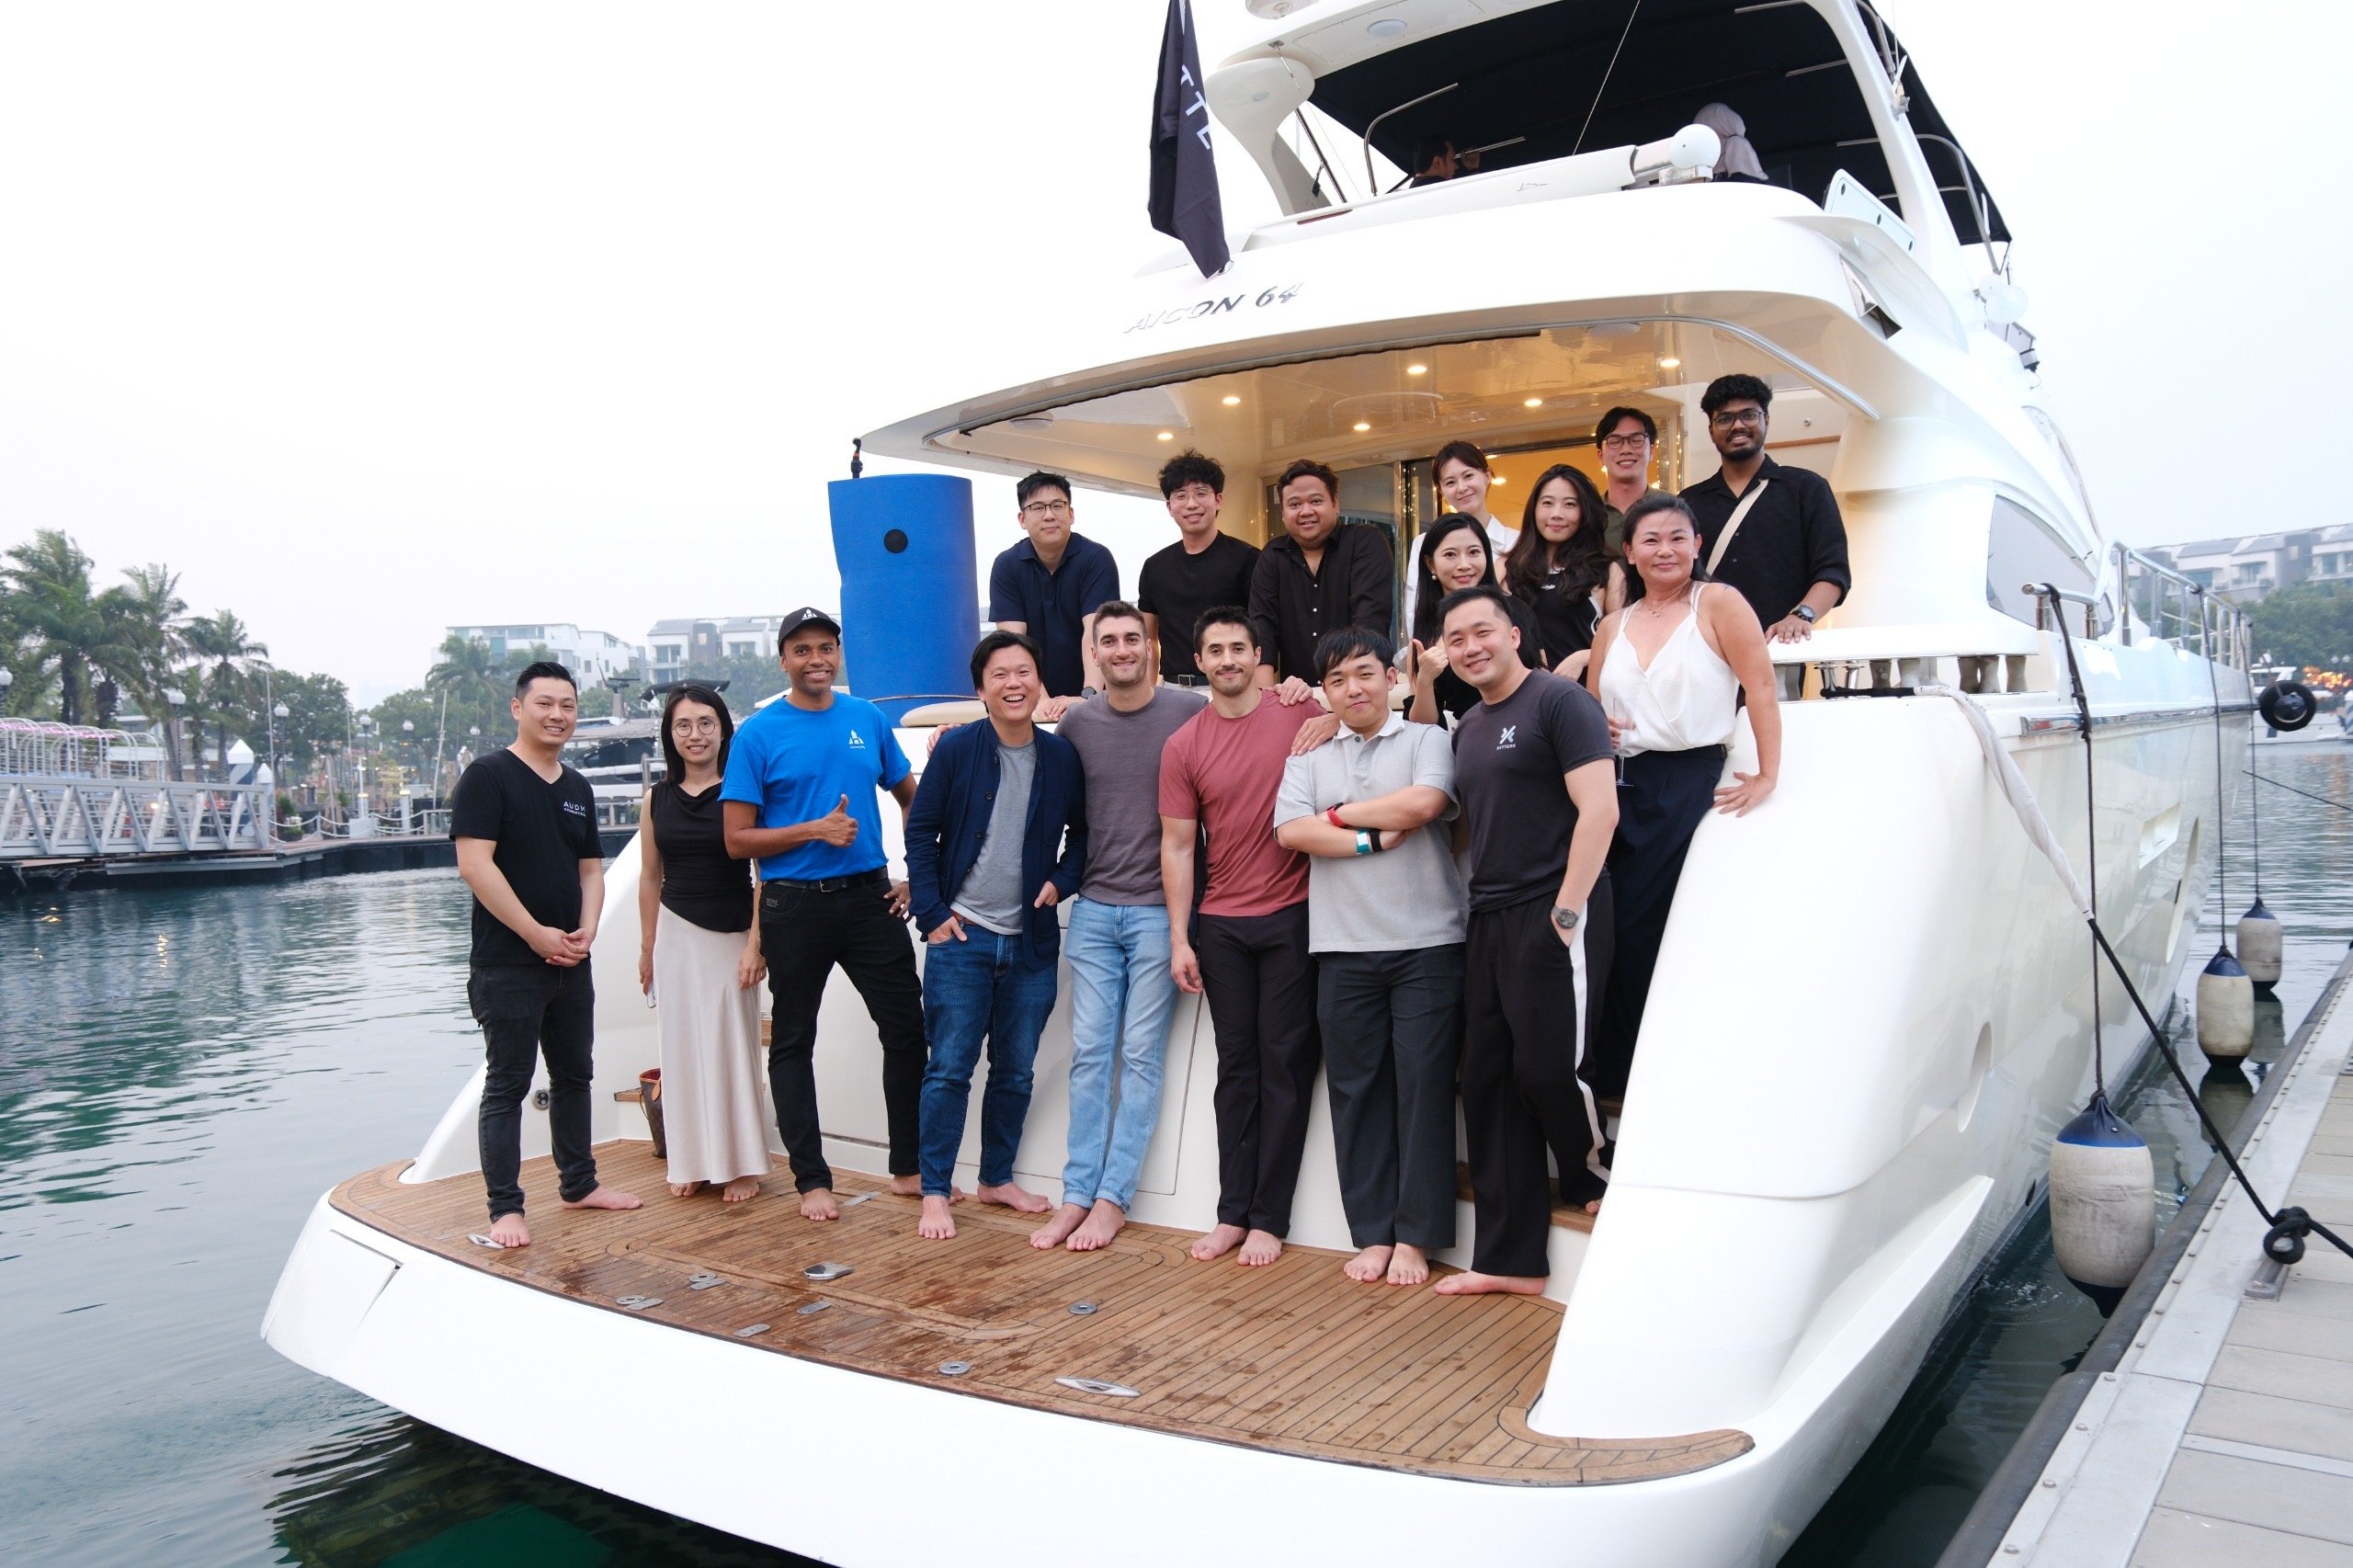
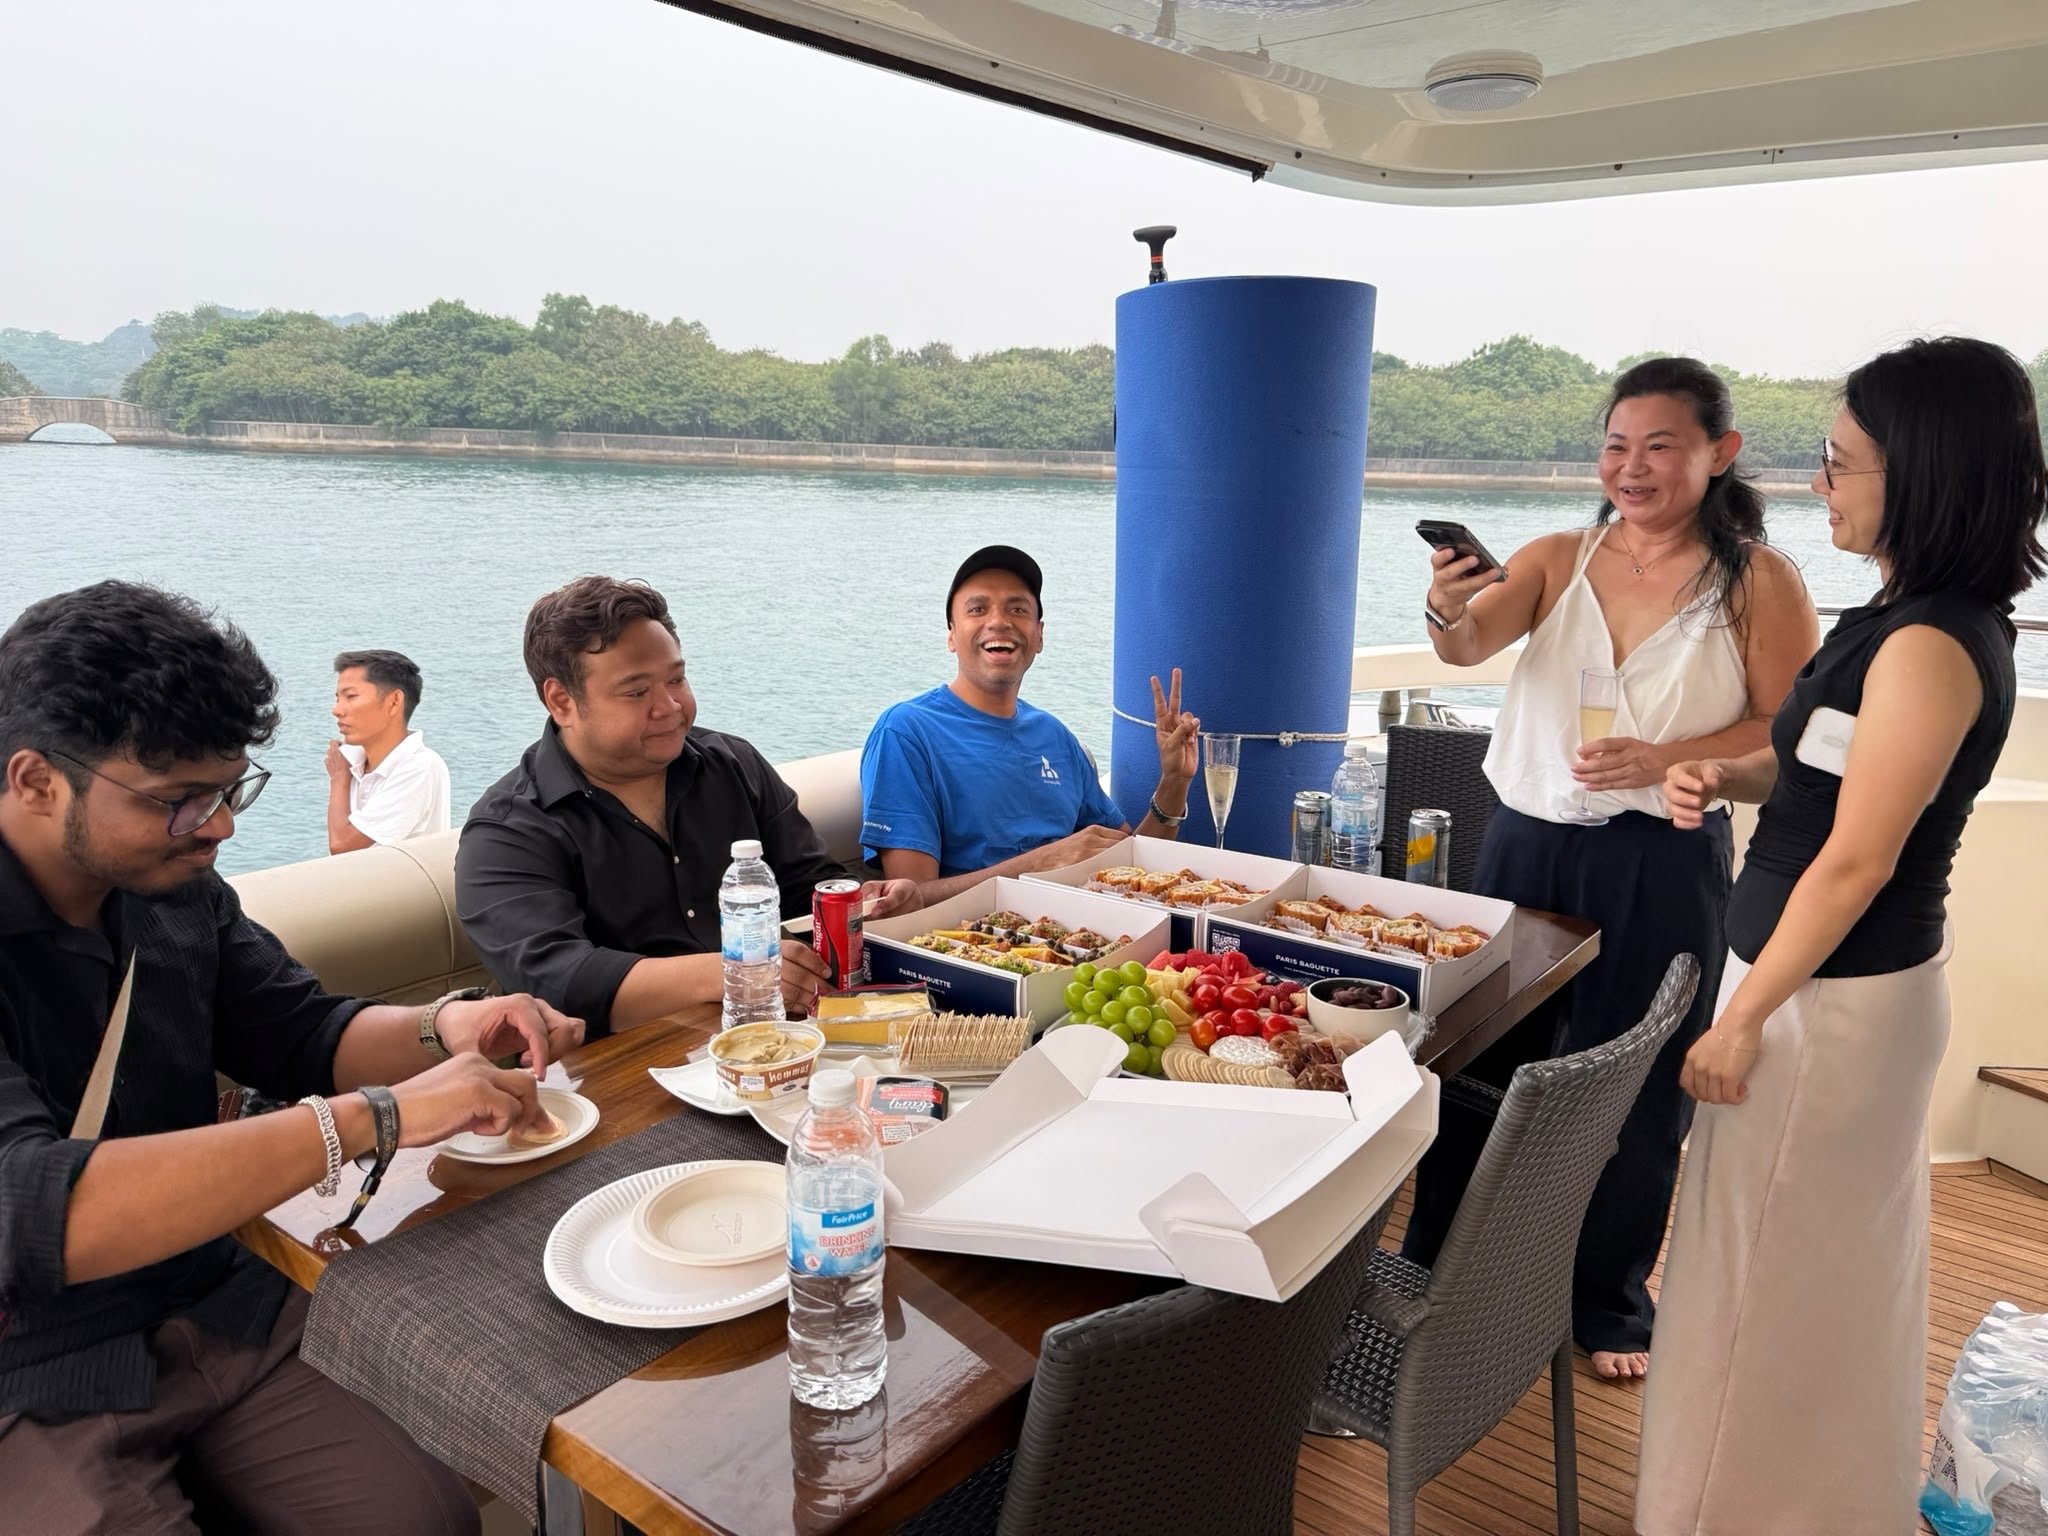
Alongside this week's industry developments, BetterX and AUDX hosted a private gathering during TOKEN2049 Singapore.
Held on Monday, 5 October, the evening brought together representatives from across the digital-asset ecosystem for discussions on payments, stablecoins, yield and institutional markets.
With participants from organisations including DCG, Hashed, HashKey, Kraken, Lido, DigiFT, BitGo, Reap, Morph and Alchemy Pay, the evening provided an opportunity to exchange perspectives across different parts of the market.
The setting was deliberately informal, allowing conversations to develop beyond the usual conference presentations and meeting schedules.
For BetterX and AUDX, these discussions are particularly valuable as we continue working with participants across payments, digital assets and financial infrastructure.
Thank you to everyone who joined us. We appreciated the opportunity to connect and look forward to building on those conversations.
Thanks for reading X Change.
We'll be back next Friday with another briefing on the developments shaping digital assets, stablecoins and financial infrastructure.